
Demo 3: portfolio, fixed-split models, and engine candidates
A standalone screenshot-led tutorial: portfolio, fixed-split models, and engine candidates, from configuration to result checks.
Before you begin
This tutorial records the unpublished main source candidate 0.2.0rc1. Bring your own local data and freeze it using the shared preparation guide. Results remain RESEARCH-ONLY with PIT guarantee false.
Shared preparation: select and freeze data
Run the composite strategy
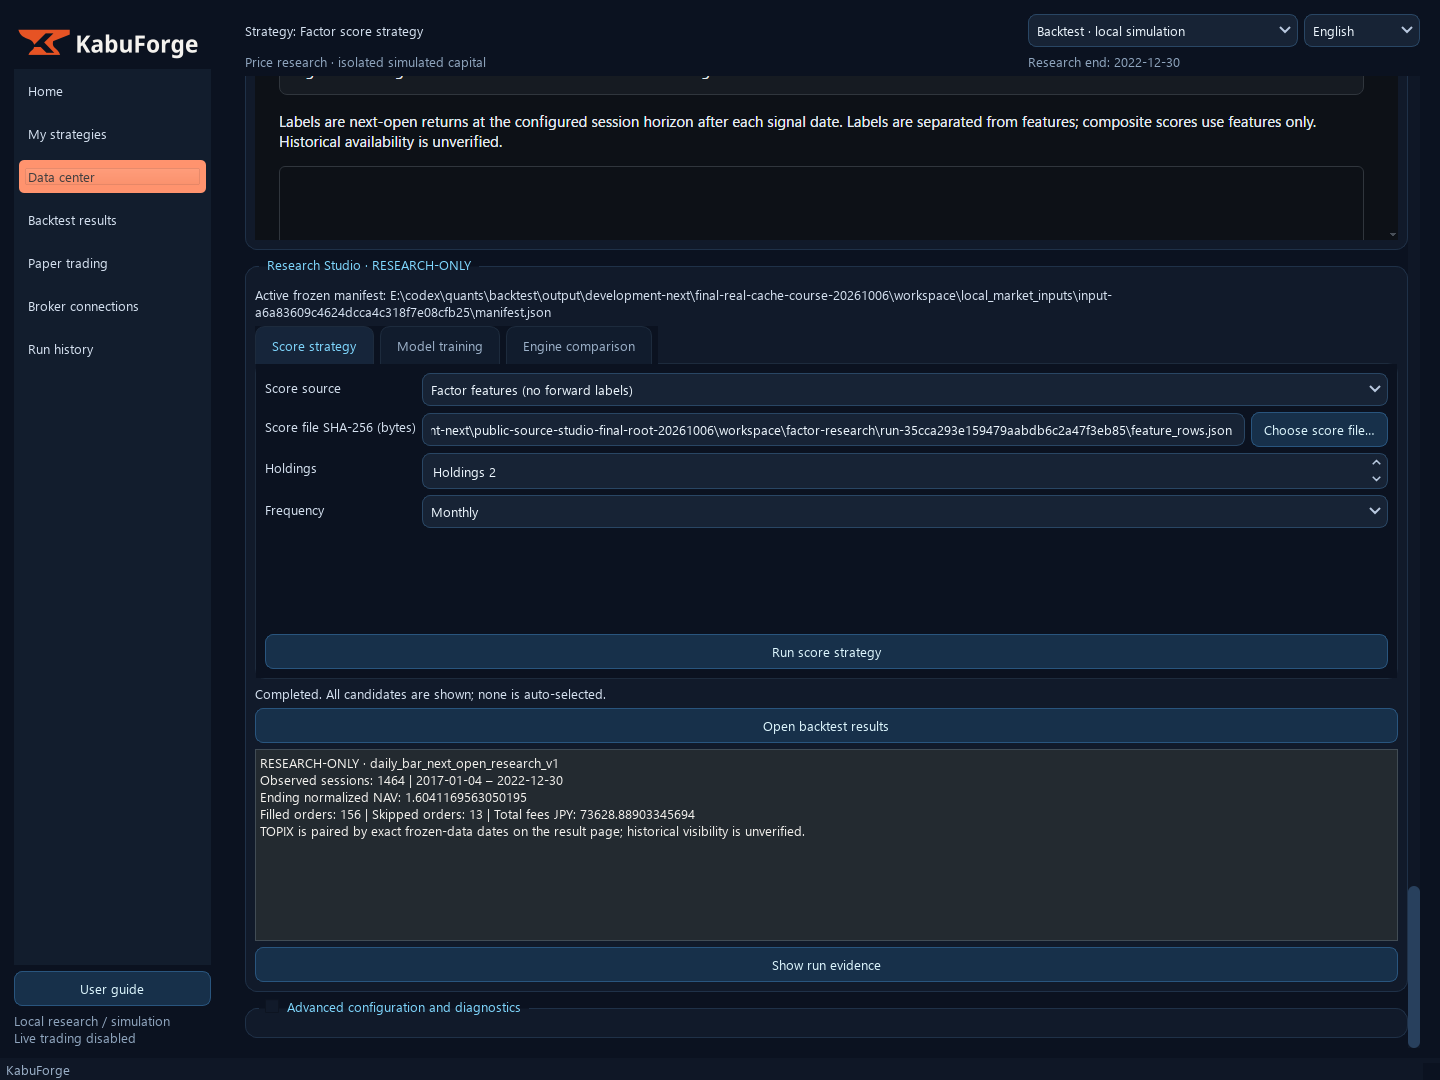
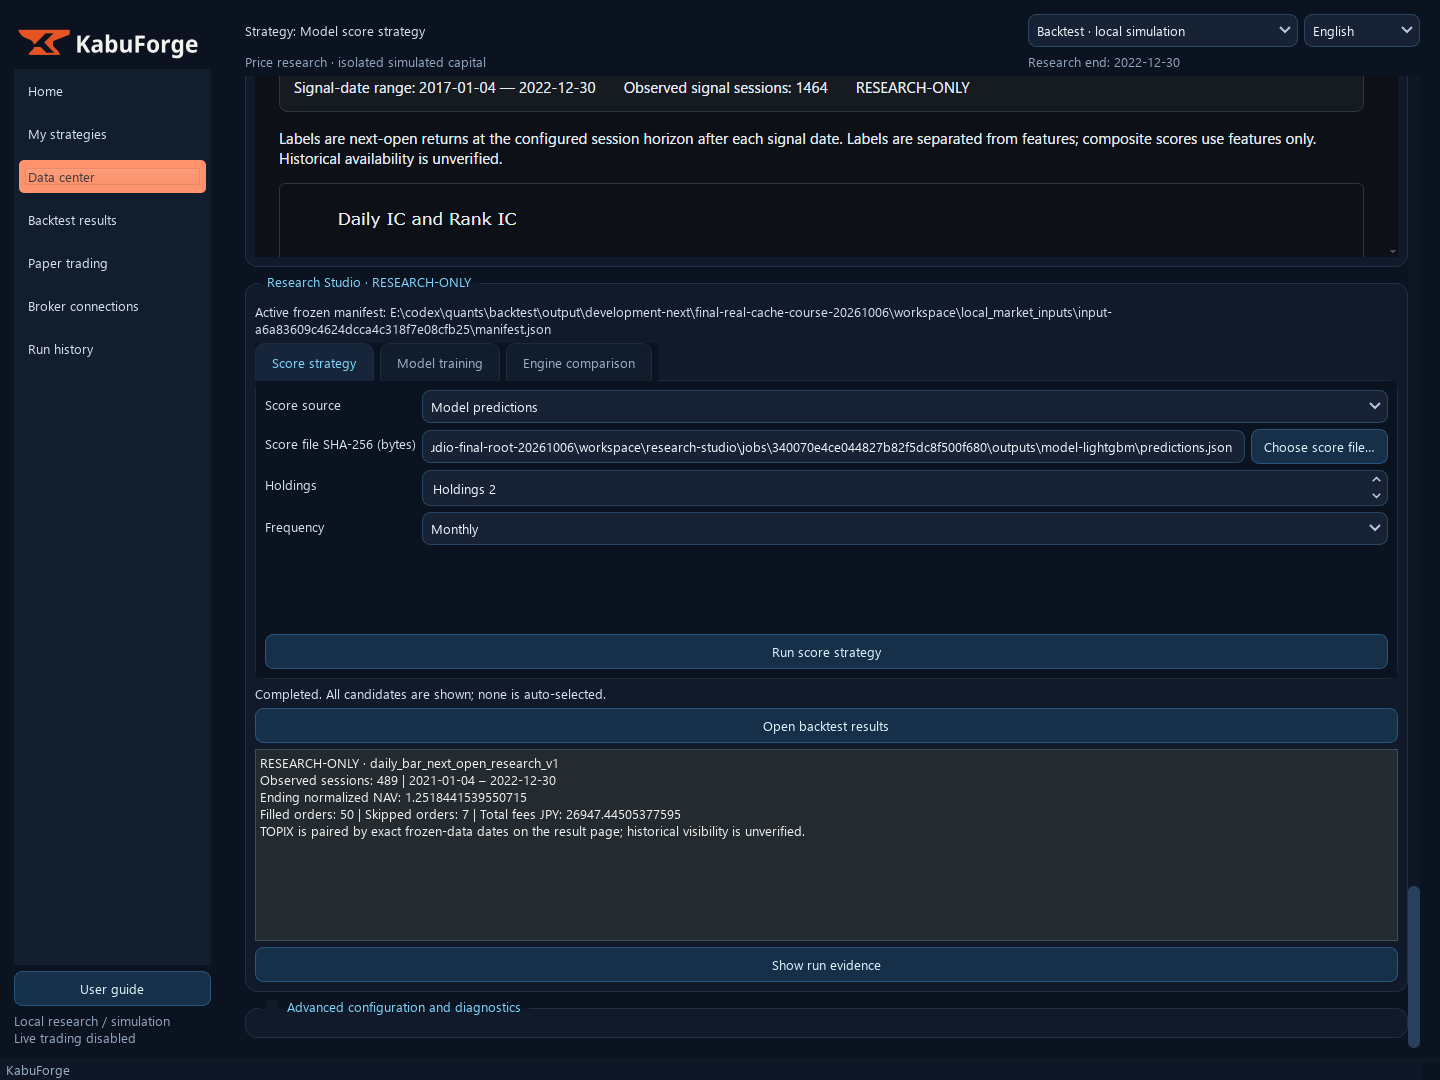
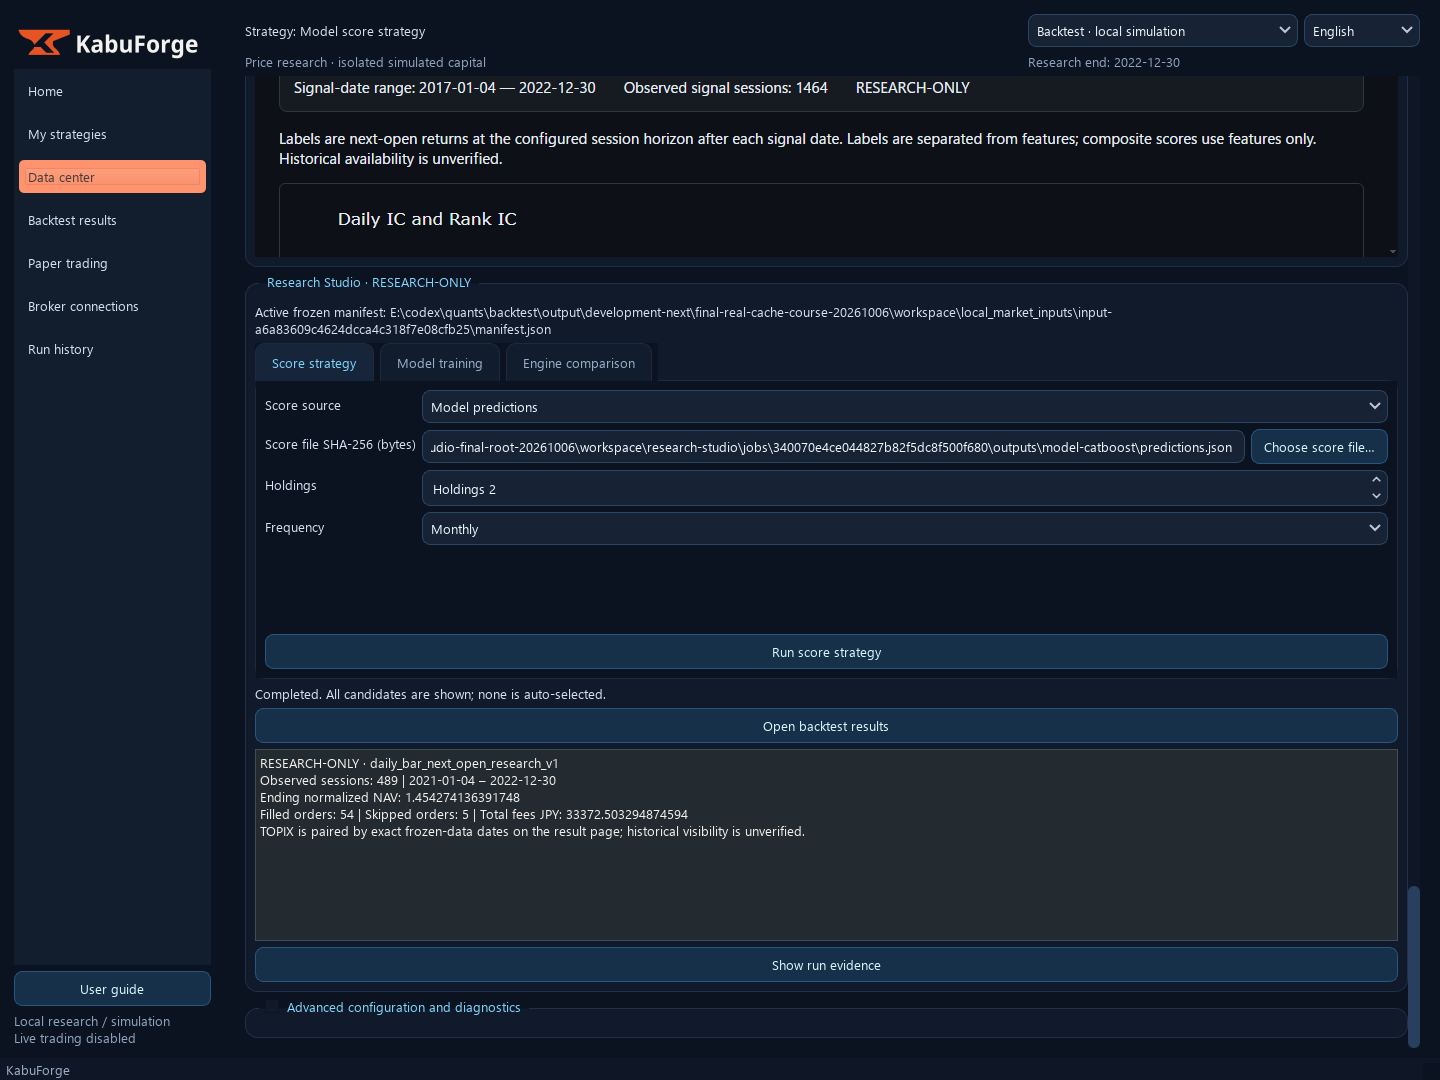
Open “Data Center → Research Studio”. In “Strategy”, explicitly select factor_feature_rows (feature-only) or a completed model predictions file, then verify its byte SHA. Do not select evaluation/forward-label artifacts. Keep two holdings, monthly rebalance, JPY 2,000,000, 0.1% one-way fees, minimum cross-section 3, and the positive 20/60 composite weights of 0.5 each.
After running, inspect signal and execution dates, actual fills/skips, and daily NAV.
Train the fixed-split models
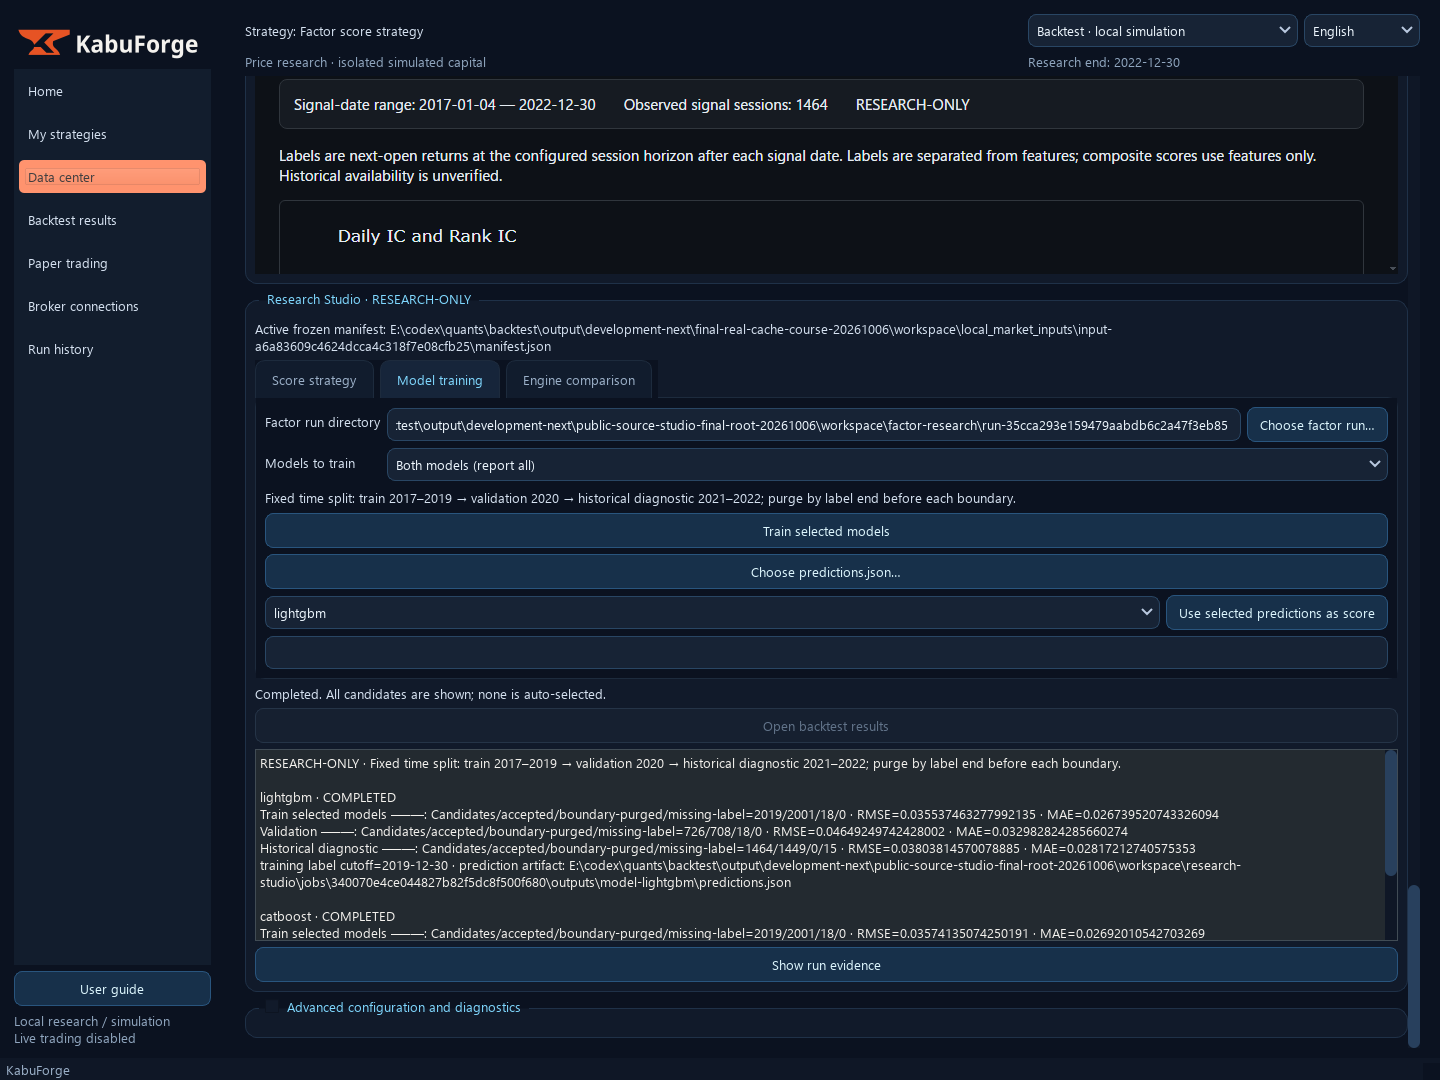
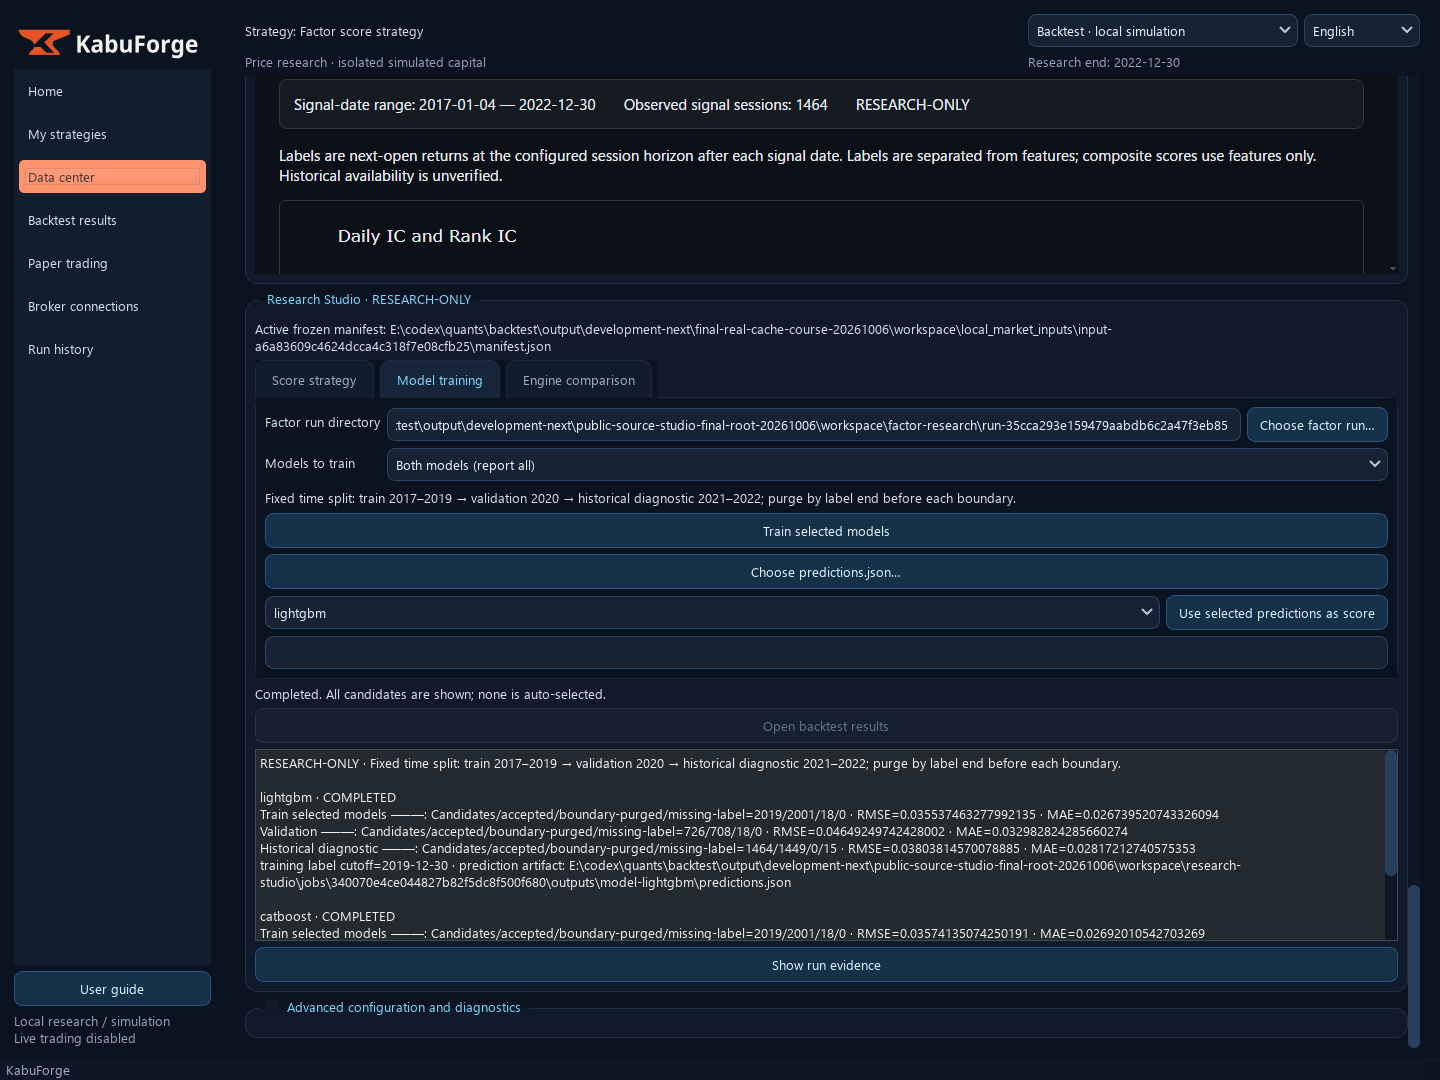
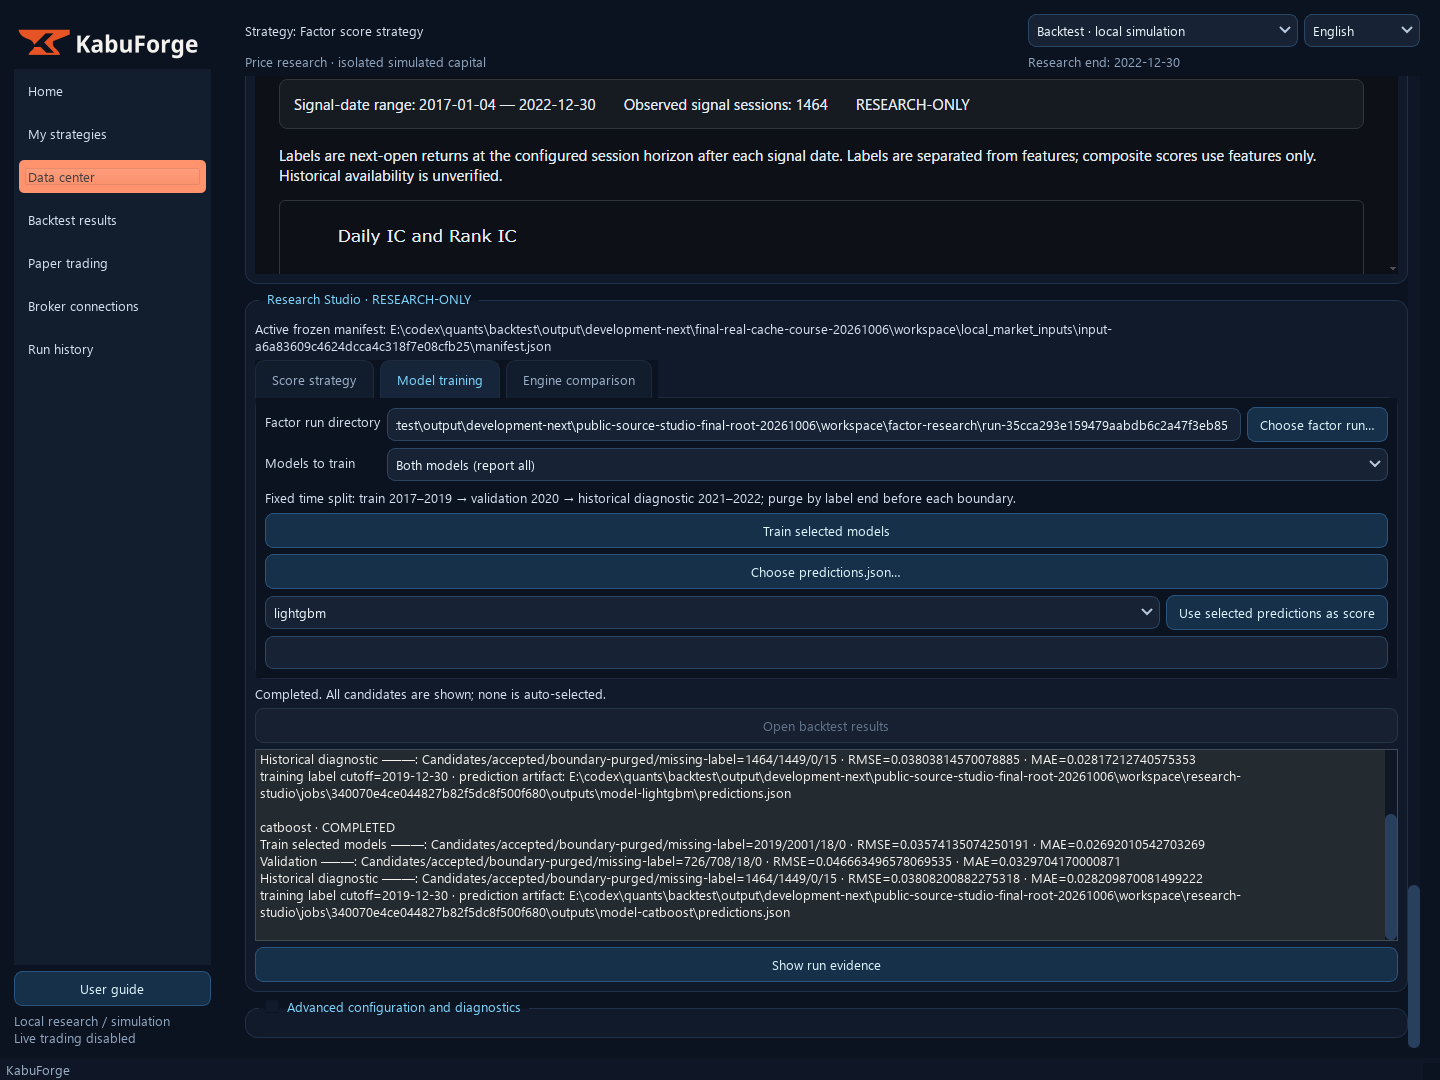
In “Models”, select the frozen factor run and run both LightGBM and CatBoost fixed models. The split is train 2017–2019, validation 2020, historical diagnostics 2021–2022, seed 42, with label-end purging at boundaries. There is no random split, auto-tuning, or automatic model selection.
Training-fit predictions are diagnostic only and must not enter strategy predictions. Verify the model is used only after its training-label cutoff. 2021–2022 is already observed history, not fresh OOS. Preserve split counts, purge counts, missing reasons, and model/prediction hashes.
If an isolated dependency fails, use its stage and worker log; do not import it into the main process.
Compare execution engines
In “Engines”, inspect Native, VectorBT, and Backtrader reports separately for the same manifest and frozen order recipe. Candidates replay fixed quantities and must not copy Native NAV. Daily account tolerance and execution-stream equality are separate outcomes.
Compare fill date, side, quantity, actual open price, fee, skips, and account path. Preserve cash and long-only semantic differences; close cash alone does not prove equal execution. A Backtrader next-bar market event is not a broker fill.
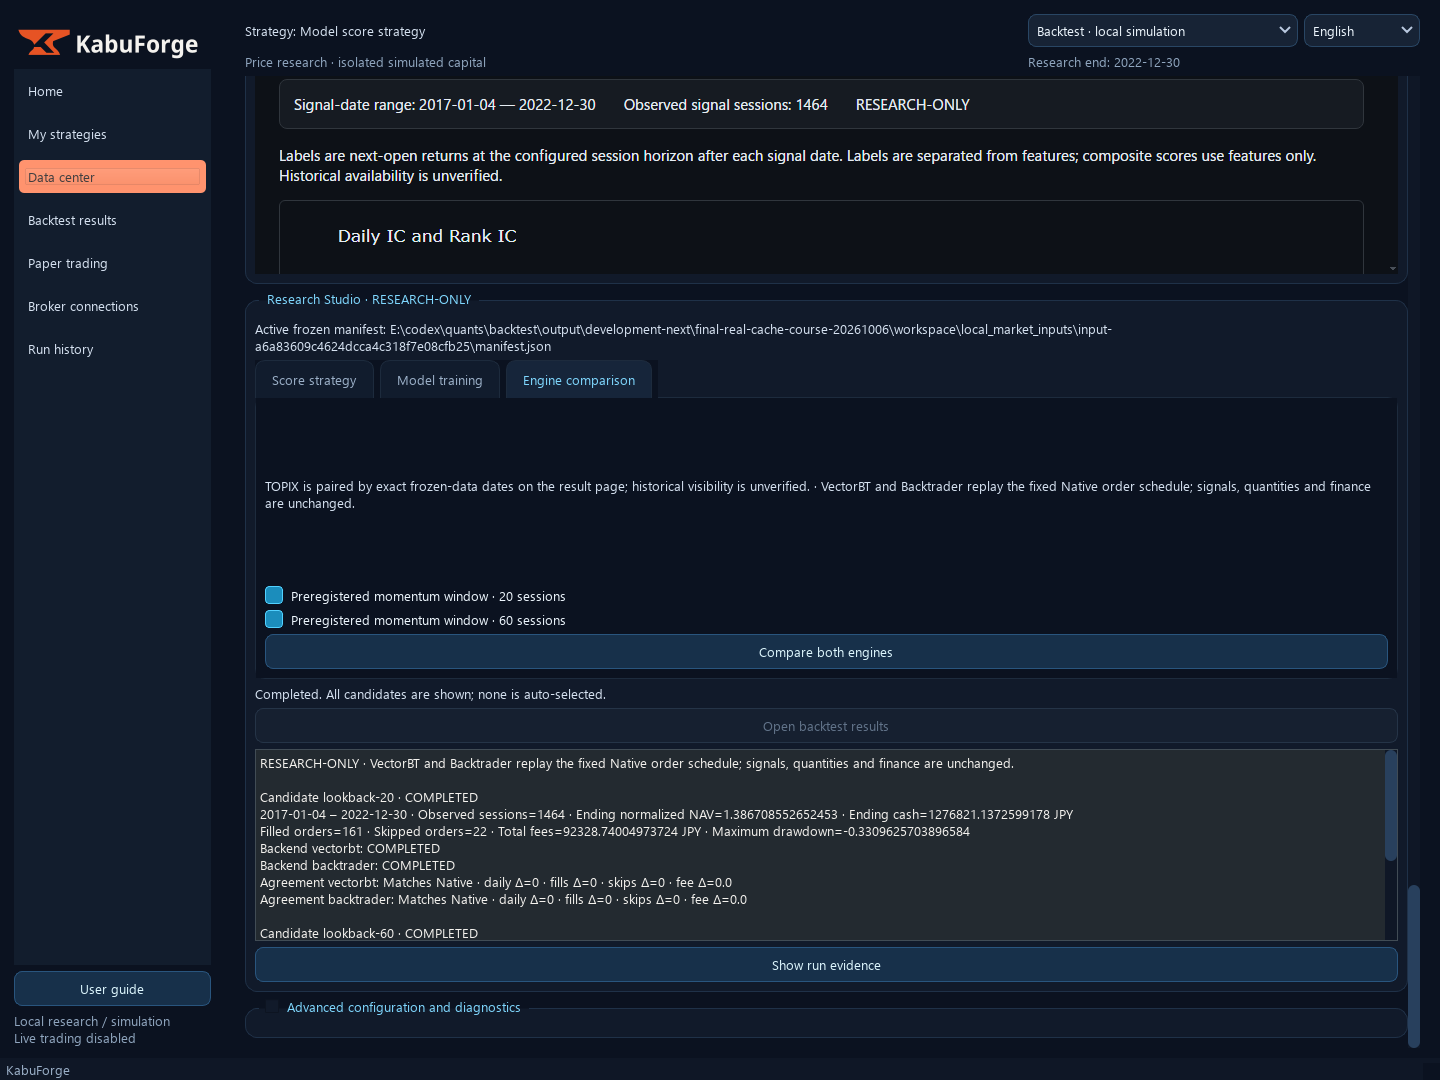
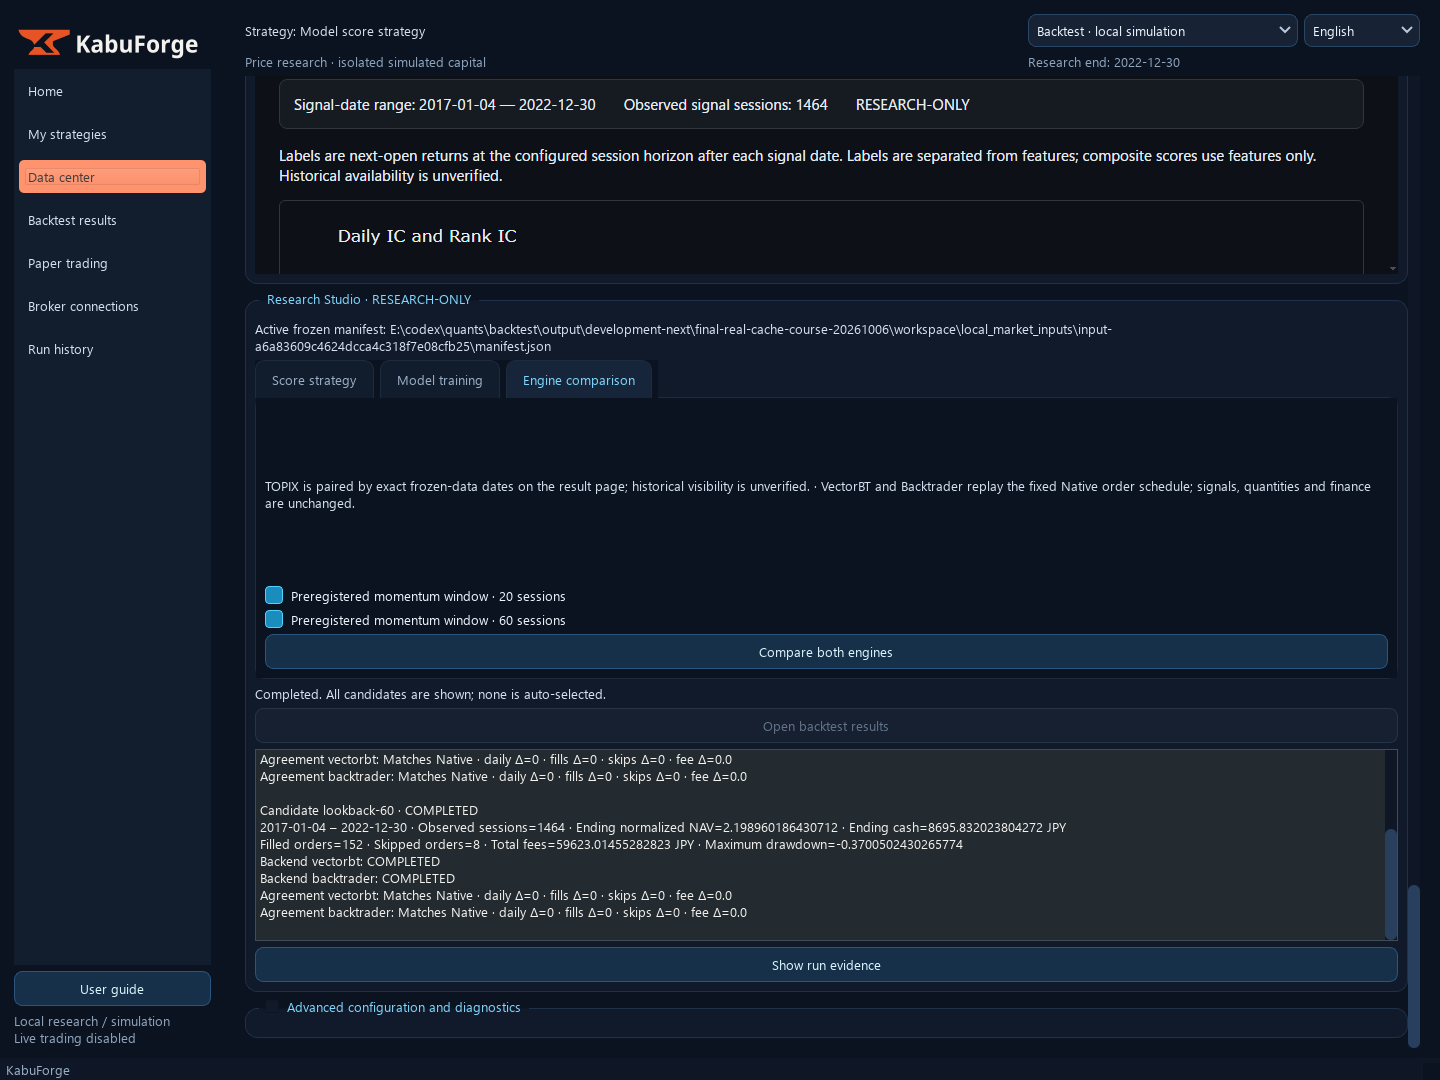
Inspect accounting before charts
Read the account path, order schedule, fee evidence, and report/source hashes before interpreting charts. The actual TOPIX price index excludes dividends and is comparable only on exactly aligned NAV dates; missing dates make relative statistics unavailable.
The dashboard has 19 figures: 15 overview figures, 3 per-security price/execution figures, and 1 Regime-state figure. In this report that figure is Off/unavailable with zero traces and no qualified state trajectory. Fee and execution-delay sensitivity runs use a separate panel and are not included in these 19 figures.
All outputs remain RESEARCH-ONLY/PIT false.
Continue learning
All five tutorials · Quantitative research basics · Reading result charts
Applies to: main source candidate (unpublished) · Public source docs/en_US/GUI_RESEARCH_COURSES.md
Reviewed · KabuForge