
JAPANESE EQUITIES · LOCAL RESEARCH · OPEN SOURCE
Explore Japanese equities.
Build your research.
Use J-Quants or your own local data to explore factors, backtest strategies and inspect portfolios through a desktop GUI. Follow the existing courses one step at a time.
Stable release v0.1.1 · Check installation requirements
View source on GitHub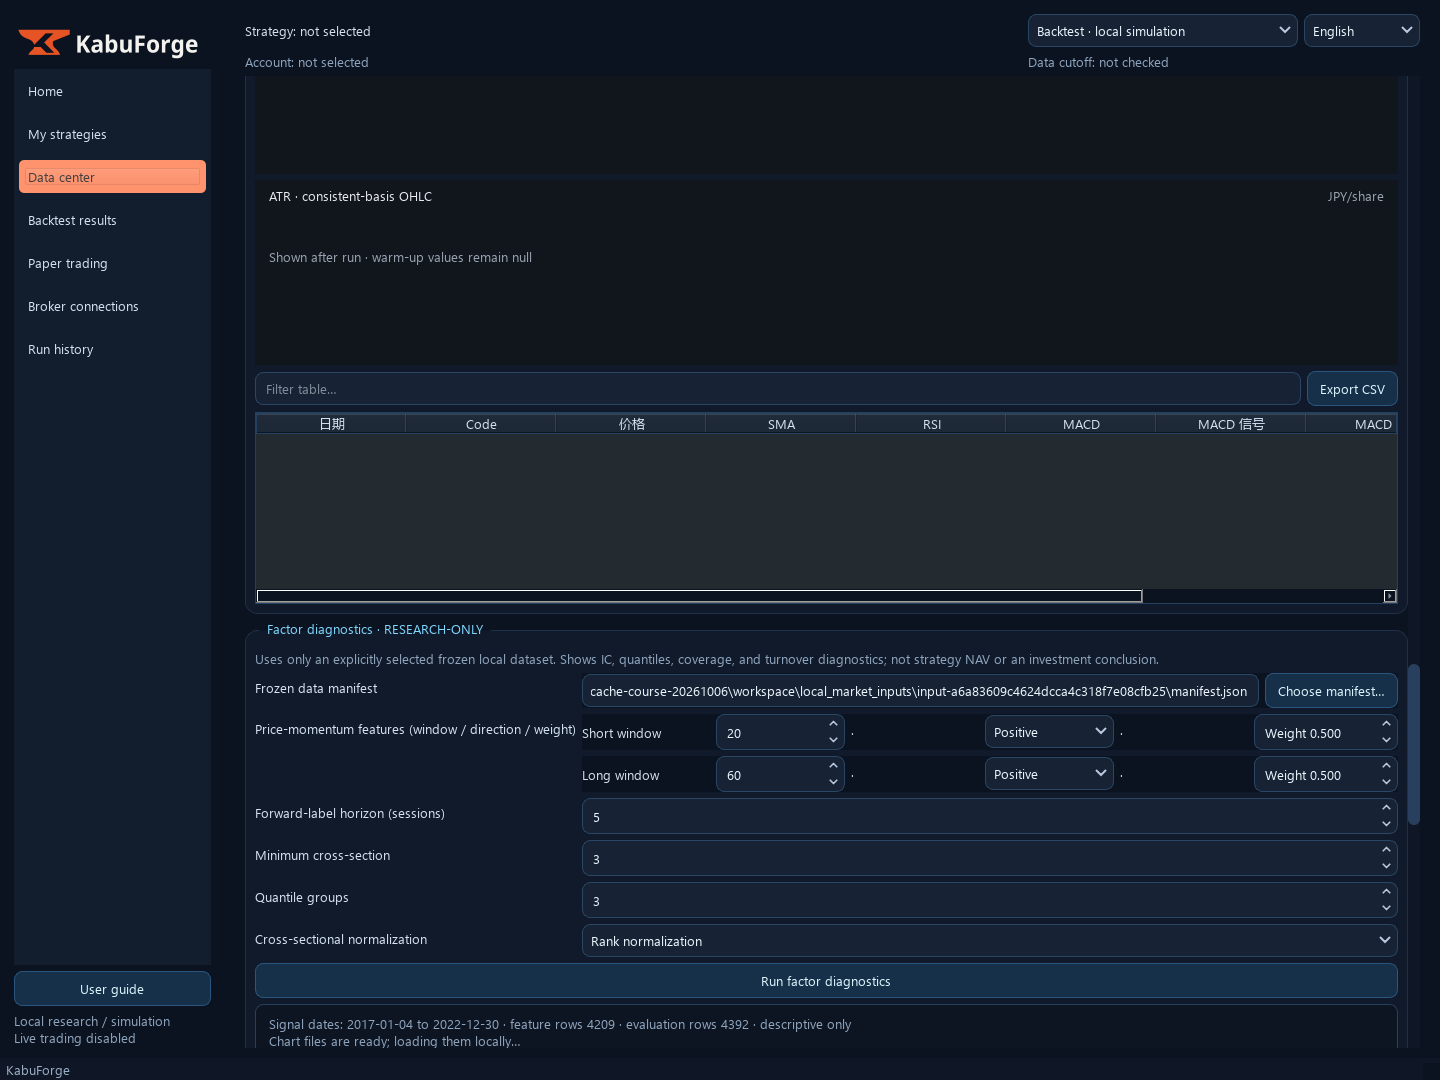
WHAT YOU CAN DO
From local data to results you can inspect.
Load your data
Select local CSV or Parquet and freeze the research input.
Run a backtest
Choose trading assumptions and fees before examining history.
Follow the workflow on real screens.
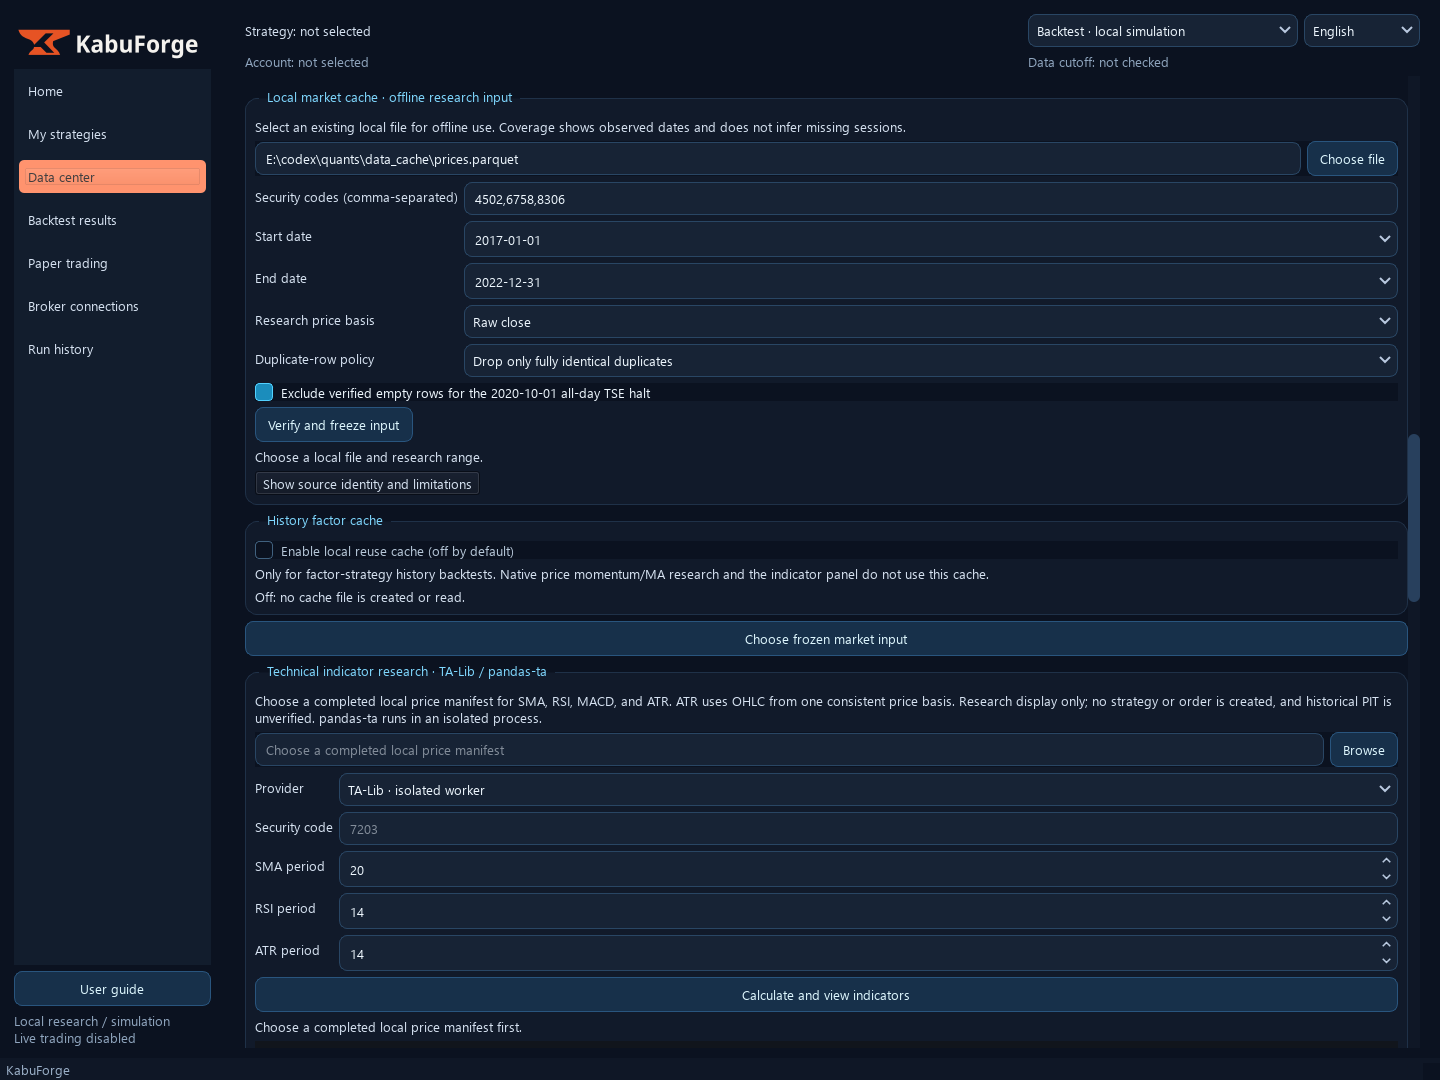
Select your input
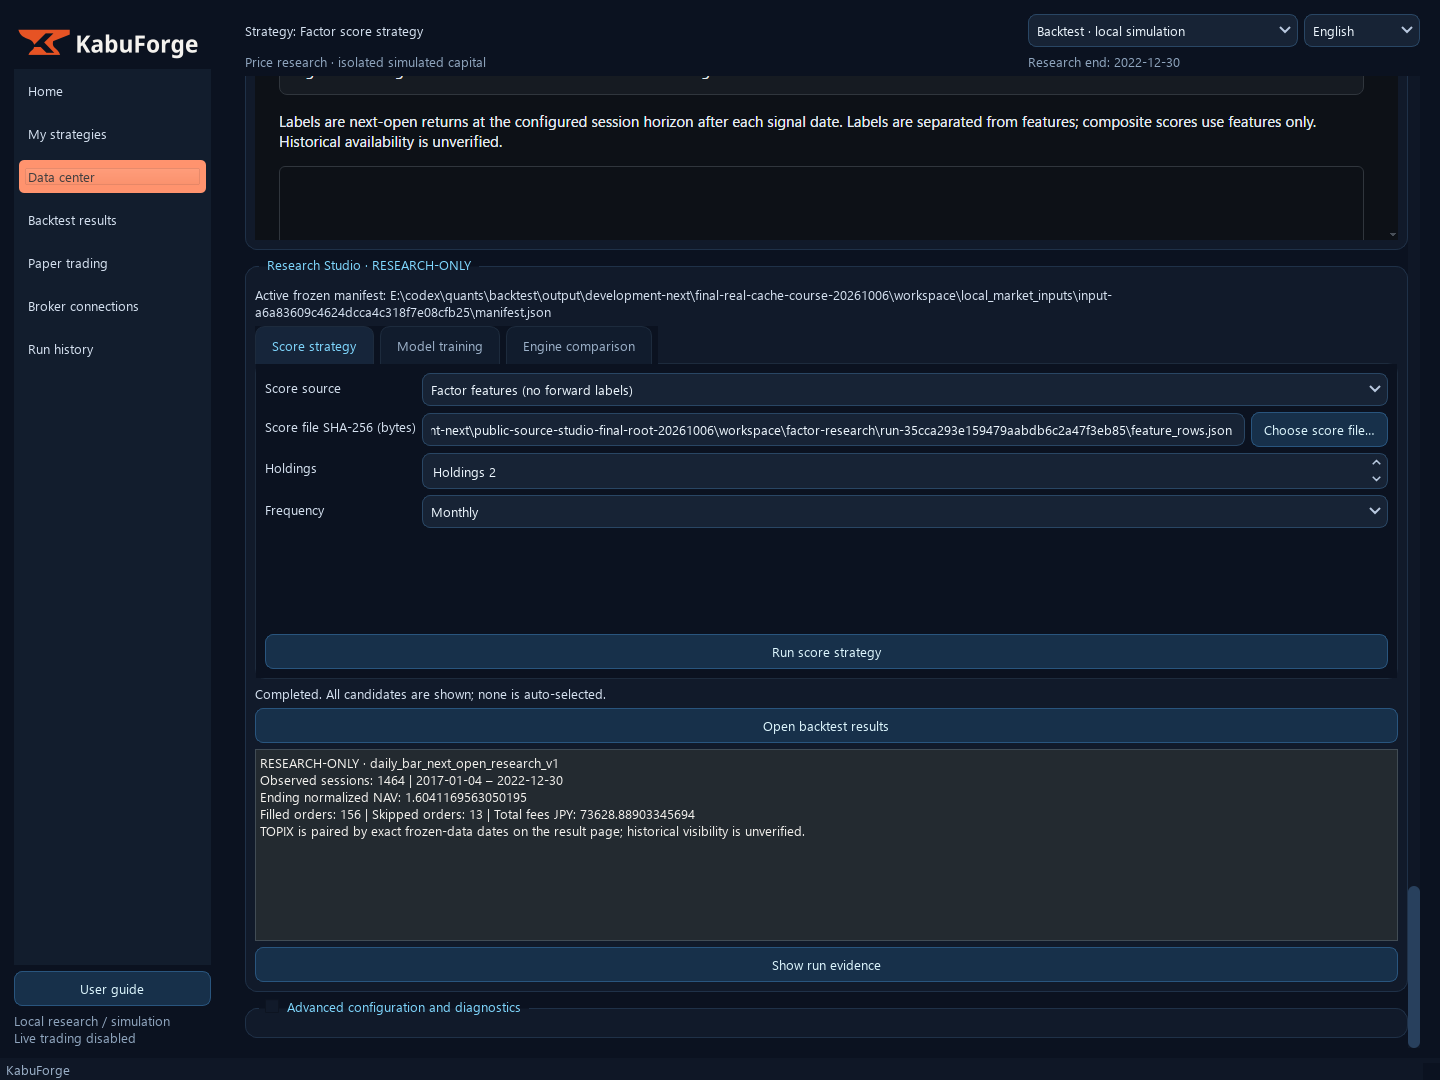
Explore factors and portfolios
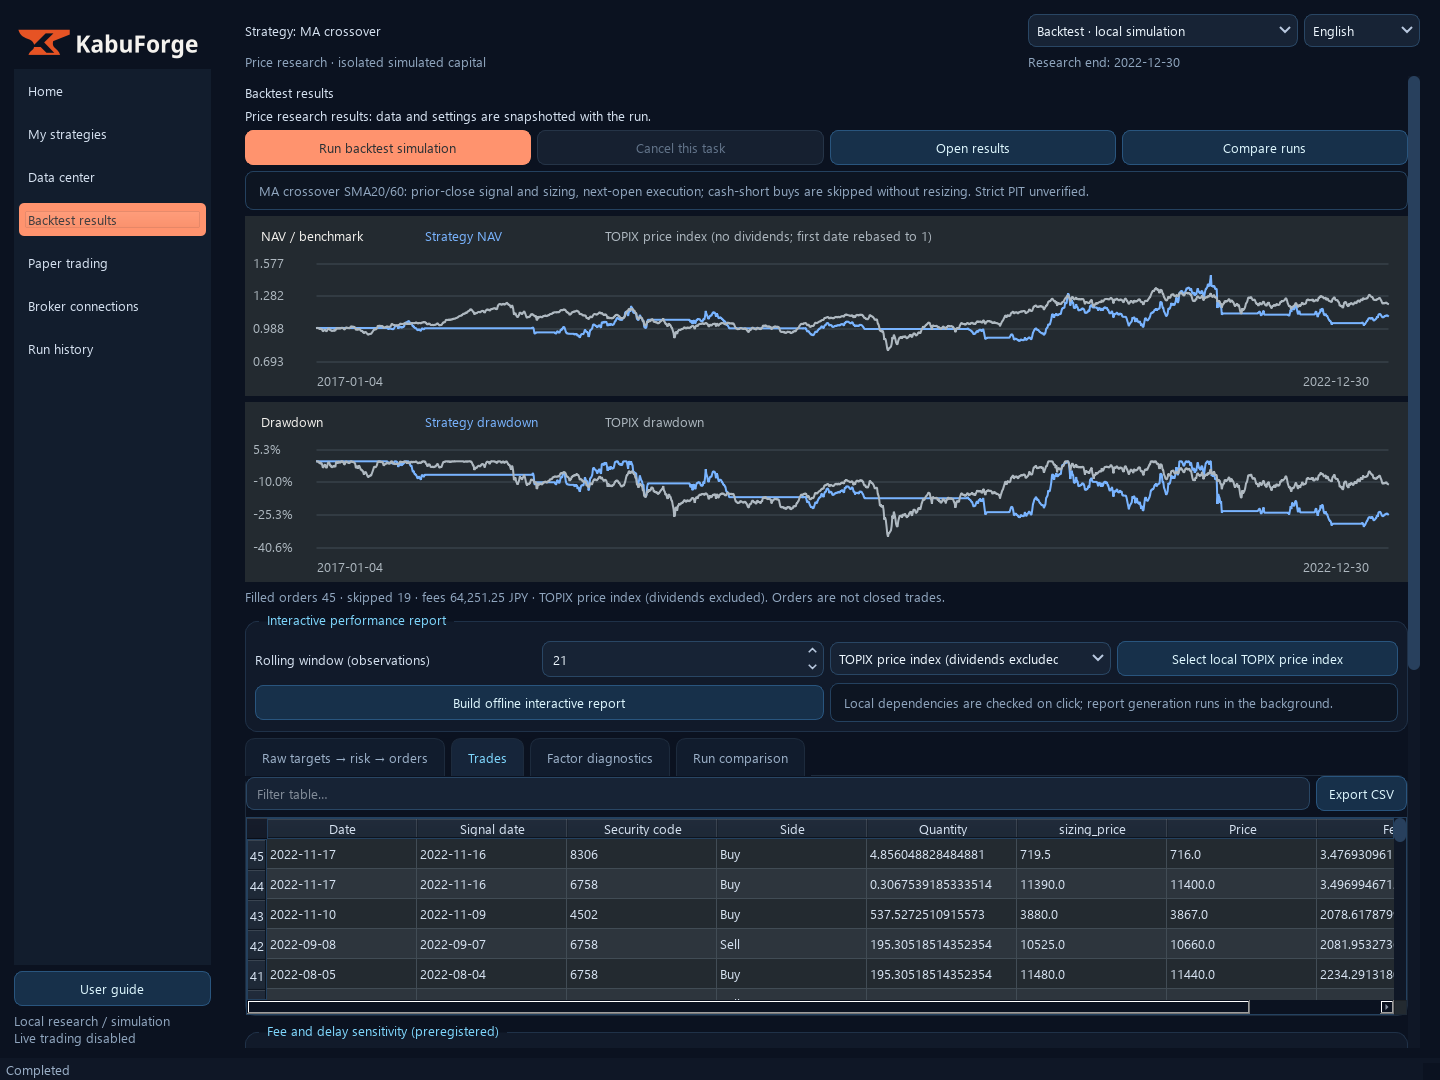
Read fills, fees and skips
Screenshots reuse existing courses from the main source candidate; they do not certify the stable package installation.
Complete your first research workflow.
- Check installation requirements
- Choose synthetic or your own data
- Select a factor or strategy
- Freeze inputs and run
- Read results and limitations
LEARNING PATHS
Learn with the existing material.
Choose a learning path through research methodology, five GUI courses and runnable examples.
Explore learning paths →Keep the inputs. Inspect the assumptions.
Research inputs stay local, and market history is not bundled. Course results are RESEARCH-ONLY with PIT guarantee false. Real order submission and cancellation are disabled.
Research methodology and limitations